Houston employee benefits · Serving Texas since 2008

Employee benefits built around relationships — not call centers.

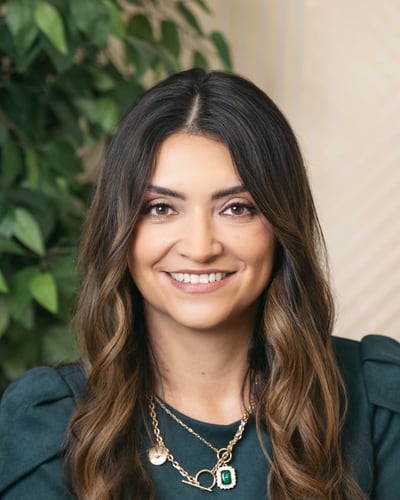
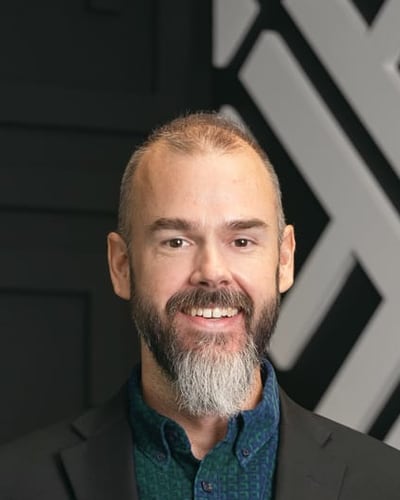
We’re Julie and Cody Wall. We place group medical, dental, vision, life and disability plans for Texas businesses from 2 to 1,000 employees, then stay on the line all year for the claims, the enrollments and the compliance. No annual disappearing act.

Julie and Cody Wall going through plan options with a client at their office.

Julie & Cody WallYour Houston benefits advisors

5.0 Google reviews
  • In benefits since 2008.

    Both of us, on the same side of the desk.

  • Third generation.

    Cody’s family has been placing benefits in Texas for about 60 years.

  • English and Spanish.

    Cody runs the enrollment meetings, and Julie runs them in Spanish.

  • Employee Navigator included.

    Benefits and HR software, set up by us, at no cost to you.

Why most people call us

The renewal letter arrived. Your broker didn’t.

It’s the same story most of our clients tell us. The rate went up again, nobody explained why, and the person who sold them the plan has not been in the office since the day they signed.

The increases are real. Small group premiums rose a median of 11% for 2026 across the country, and Texas carriers have filed for a 16.9% weighted average increase for small groups in 2027. What isn’t inevitable is going through it on your own.

Sources: KFF analysis of 2026 preliminary rate filings; Texas 2027 preliminary filings via the federal Rate Review database. 2027 rates are requested, not approved.

An opened renewal letter on a desk beside a cup of coffee and reading glasses.

Beyond the policy

Anyone can sell you a plan. This is the part that’s different.

An open enrollment meeting in a warehouse break room, with employees asking questions.
  1. Your employee calls a person, not a phone tree.

    When someone on your team gets a bill they don’t understand, or a claim gets denied, or a new hire needs adding halfway through the year, they call us. We work it with the carrier and report back. In English or Spanish.

    That’s not an add-on service, it’s the job.

  2. We walk you through compliance. We don’t email you a PDF.

    ACA reporting, ERISA documents, COBRA, Section 125, required notices, and the non-discrimination testing that employers fail without ever knowing they were being tested.

    Julie handles the filings and Cody walks you through what each one means. Nobody here emails you a PDF and wishes you luck.

  3. Employee Navigator, set up by us, at no cost to you.

    Onboarding, elections, carrier feeds and employee self-service, so open enrollment stops being a stack of paper forms on your desk. We implement it and we run it. You don’t pay for it and you don’t set it up.

    And if you already have payroll or benefits software you like, keep it. We work with what you have. If you would rather do it on paper, we’ll do that too.

How we work

Three steps, then eleven quiet months.

A year with us

The busy month Steps 1 and 2: we listen, shop it and explain it.

The eleven quiet months Step 3: we stay involved, so you don’t have to.

  1. We listen.

    What you have now, what it costs you, what your team actually complains about, and what you want the benefits to do for the business.

  2. We shop it and explain it.

    We take it to the market, put the real options side by side, and tell you what each one means in plain language. Then we explain it to your team, not just to you.

  3. We stay involved.

    Enrollment, claims, new hires, terminations, compliance dates. All year, not just at renewal.

Changing brokers is easier than you think

It’s a one-page Agent of Record letter. Your plan doesn’t change, your carrier doesn’t change, your price doesn’t change until your renewal, your employees don’t have to do anything, and it can happen at any point in the year. You are just changing who picks up the phone.

Who you deal with

Two people, both doing this since 2008.

Julie and Cody Wall standing together.

Julie Wall

CEO & Founder · In benefits since 2008 · Bilingual

Julie built the service side of this business, and it’s still the thing she cares most about: employees get help, not just employers. She also handles the regulatory filings that keep our clients out of trouble.

Cody Wall

President · In benefits since 2008 · Third generation

Cody is third generation. His grandfather started the family agency around 60 years ago, his father took it over in the late nineties, and Cody was its president. He runs the enrollment meetings and keeps up with the rules so clients don’t have to.

Married eighteen years, in business together, raising a 16-year-old in Houston. Read the longer version

Real numbers

What does group health insurance cost a Texas business?

In 2024, employer-sponsored single coverage in Texas averaged $7,833 a year per covered employee, of which employers paid an average of $6,318. That’s roughly $650 below the national average. Small group premiums then rose a median of 11% for 2026, and Texas carriers have requested a 16.9% weighted average increase for 2027. Your number depends on your group’s age, your county, the plan design and how much of the premium you cover.

Get your actual number
  • $7,833 Average annual single premium in Texas, 2024. Employer share $6,318. KFF State Health Facts
  • $9,211 Average annual single premium at small firms nationally, 2025. KFF Employer Health Benefits Survey 2025
  • 11% Median small group premium increase filed for 2026. KFF analysis of preliminary rate filings

Texas and national figures come from different surveys and different years, so they are not directly comparable. Figures are for general information, not a quote.

What clients say

Ask them what happens in March.

5.0 Google reviews from local business owners

Jumping into navigating employee benefits and insurance with no prior experience was a little overwhelming, but they have made the entire process so easy. Any time I have a question, Julie is only a phone call away and she and her team always have a solution within minutes. It’s rare to find people like Julie and Cody with this level of expertise combined with such a personal approach.

Kaly VallejoGoogle review

As someone who’s rather new to handling employee benefits and insurance, Julie has really made it so much easier for me to learn and navigate everything. She is always quick to answer my questions and help when something comes up with one of our employees. Cody has also been great to work with and has gone above and beyond for us. He has created tools to help us evaluate our benefit options and even put together a video for our employees explaining our insurance coverage.

Courtney VincekGoogle review

Great company! They are very knowledgeable, professional, and always respond in a timely manner. I’ve had a great experience working with them and highly recommend their services!

YvonneGoogle review

Reviews quoted as written and trimmed only for length. Read them all on Google

Industries we serve

We know your kind of payroll.

Benefits look different in a machine shop than they do in a doctor’s office. Hourly crews, seasonal work, high turnover and teams that don’t all speak English change what a plan needs to do, and we’ve built for all of it.

Answers first

Common questions

Something else on your mind? Call us.

713-714-3277
How many employees do I need to offer group health insurance in Texas?

Texas defines a small employer as one with an average of at least two and no more than 50 employees, and at least two on the first day of the plan year. An eligible employee is one who usually works at least 30 hours a week. So two enrolled employees is generally the floor.

Source: Tex. Ins. Code §1501.002

Does a Texas small business have to offer health insurance?

No. The federal employer mandate applies to employers with 50 or more full-time equivalent employees. Below that there is no requirement to offer coverage. Most of our clients offer it because they’re competing for the same people the big employers want.

How much of the premium does the employer have to pay?

Texas law does not set a general minimum employer contribution for the open small group market. In practice most carriers require the employer to pay at least half of the employee-only premium, and Texas law does require at least 75% of eligible employees to enroll. Requirements vary by carrier and we confirm them when we quote.

Source: Tex. Ins. Code §1501.154

What is the difference between a fully insured and a level funded plan?

With a fully insured plan you pay a fixed premium and the carrier takes all the claims risk. With a level funded plan you pay a fixed monthly amount that covers claims, administration and stop-loss cover, and if your group’s claims come in low you may get money back at the end of the year. Level funding can suit a younger, healthier group. It also carries more variability.

Does using a broker cost more than going direct to the carrier?

No. Broker compensation is built into the carrier’s rates whether or not you use one, so the premium is the same. The difference is whether anyone helps you compare the options, run the enrollment and deal with the claim when it goes wrong.

How do I switch brokers, and will it disrupt our plan?

You sign a one-page Agent of Record letter naming us on your existing policy. The plan, the carrier, the network and your employees’ cards all stay the same, and so does your price until your renewal. It can be done at any time of year, not only at renewal.

Get in touch

Call us. You’ll get a person who knows your plan, not a menu.

713-714-3277

Monday through Friday, 8:30am to 5:30pm.

If we miss your call, we may text you back from this number. We never send marketing texts. Reply STOP to opt out. How we use texts

Or send the form and we’ll get back to you the same business day.

The Clever Insurance a trading name of Clever Benefit Solutions LLC 6220 Westpark Dr, Suite 115 Houston, TX 77057 service@cleverbenefitsolutions.com

Or ask us for a quote

We’ll never share your details or add you to a mailing list. A real person reads every one of these.

Call Get a quote